

Commentary
Datatec is an international ICT solutions and services group operating in more than 50 countries across North America, Latin America, Europe, Africa, Middle East and Asia-Pacific. The Group's service offering spans the integration and managed services, technology distribution and management consulting sectors of the ICT market.
 JENS MONTANANA,
CHIEF EXECUTIVE OF DATATEC, COMMENTED:
"Datatec's first half results were supported by excellent operational execution with all divisions delivering strong top and bottom-line growth as the positive impact of increased digitisation on recurring software and services continues."
"Based on the Group's healthy financial position and following the repayment of loans by Westcon International put in place at the time of the SYNNEX transaction, the Board is pleased to return the proceeds to shareholders through a US$70 million special dividend."
"The Strategic Review announced recently is also progressing with several options and initiatives under review to unlock and maximise further shareholder value. We are seeing pent-up demand in many forms across the world and expect a strong performance throughout the second half of the year, however the semiconductor shortage is expected to continue to result in significant backlogs across the Group well into 2022."
Our three core divisions
International solutions provider of digital services currently accelerating the digital transformation of its 10 000 global customers
Over 6 000 employees
Over 25 countries worldwide

Logicalis drives digital enablement through a variety of services including:
- Integrated and professional services
- Lifecycle and managed services
- Cloud solutions
Customer advocate with some of the world's leading technology companies including Cisco, IBM, Microsoft, Oracle, HPE, NetApp and VMware
Operates in Europe, North America, Latin America, Asia-Pacific and Africa
Value-added technology distributor of industry-leading solutions
Class-leading cyber security, network infrastructure, unified collaboration products, data centre solutions and channel support services
Datatec Financial Services
Provides innovative financial solutions to Datatec Group customers
Over 3 000 employees
Over 50 countries worldwide
Goes to market under the Westcon and Comstor brands
Westcon International's portfolio of market-leading vendors includes, Avaya, Broadcom, Check Point, Cisco, CrowdStrike, Extreme Networks, F5, Infoblox, Juniper, and Palo Alto Networks
12 000+ partners
18 logistics and staging facilities throughout Europe, Asia, Australia, New Zealand, Middle East and Sub-Saharan Africa
Datatec Financial Services
A specialist team of financial
experts who support the
Datatec Group and
any partnering organisations
Provides customers with a financed alternative method of acquiring technology hardware, software and services
Analysys Mason
World’s leading management consultancy focused on telecommunications, media and technology (“TMT”)
Over 300 employees
Over 10 countries worldwide
Analysys Mason
Provider of strategic, trusted
advisory, modelling and market
intelligence services to the
TMT industries
Our strategy
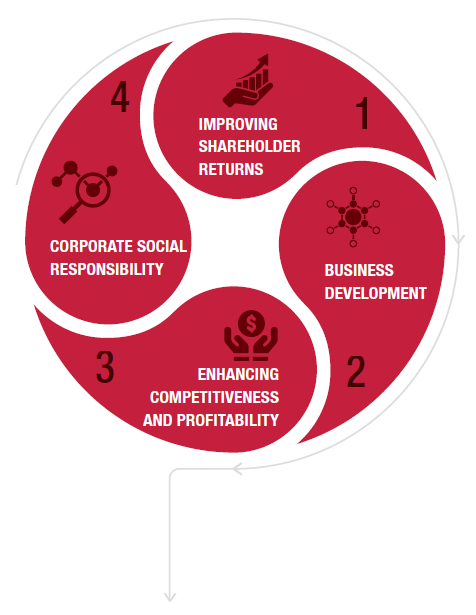
Datatec's strategy is to improve shareholder returns over the medium term through a combination of corporate and business development actions aimed at enhancing the competitiveness and profitability of its subsidiaries and operating divisions. In executing its strategy, Datatec is cognisant of its corporate social responsibility.
- Logicalis
Logicalis' strategy is to be the leading ICT services and solutions partner to customers in its key markets around the world. - Westcon International
Westcon International's strategy is to be the leading value-added distributor for cyber security and networking vendors across Europe, the Middle East, Africa and Asia-Pacific. - Analysys Mason
Analysys Mason's strategy is to focus on specialised research and management consulting in the TMT sector with international coverage. Analysys Mason's approach is based on a unique combination of applied intelligence, independent opinions, a passion for problem-solving and consistently looking more closely and seeing further. This approach engenders strong long-term relationships with clients.
Strategic overview
The Group achieved a strong operational performance in the six-month period ended 31 August 2021 ("H1 FY22") as it continued to benefit from remote working, increased cloud usage and secured networking trends. All divisions delivered strong revenue and profit growth.
The global semiconductor shortage created extended lead times on certain hardware product deliveries in H1 FY22 which somewhat restricted revenue and resulted in significantly higher closing backlog (sales orders waiting to be fulfilled) in both Logicalis and Westcon International.
Datatec's divisions continue to focus on the products and services required to support the digitisation trend prevailing in the industry as demand for remote IT networking accelerated during the pandemic. Their businesses have already repositioned away from many forms of traditional hardware to software and services with growing annuity revenue.
Shareholders were previously advised that the Board of directors of Datatec ("Board") had engaged Lazard & Co., Limited to assist with a comprehensive evaluation of strategic options and initiatives (the "Strategic Review") to unlock and maximise shareholder value going forward.
The Strategic Review seeks to address the persistent gap between Datatec's valuation and the inherent value of its underlying assets while also ensuring that the Group is positioned to take full advantage of the positive market dynamics for its technology solutions and services.
As part of the Strategic Review, the Board is currently considering a number of potential options including, but not limited to, private equity participation, joint ventures, international listings, divisional asset unbundling and other value-creating structures.
Special dividend
Following the sale of Westcon Americas to SYNNEX in September 2017, Datatec advanced funds to Westcon International (the part of the Westcon business retained in the Group with a minority interest held by SYNNEX) to fund working capital as the business restructured. During H1 FY22, Westcon International repaid approximately US$70 million of intercompany loans to Datatec. The Board is pleased to return US$70 million to shareholders in the form of a cash dividend with a scrip distribution alternative. This is the same mechanism which was used to return US$350 million to shareholders after the original SYNNEX transaction and subsequently US$15 million from the earn-out.
Dividend policy
The Group's policy is to maintain a fixed three times cover relative to underlying* earnings when declaring ordinary dividends. The Board currently expects to pay a full year dividend.
^H1 FY21 revenue restatement
The Group sells certain software, software services and cloud computing solutions which include Infrastructure as a Service ("IaaS") and Software as a Service ("SaaS"). As disclosed in the FY21 published results, these amounts grew in significance for the Group and the Group revisited the revenue recognition for these arrangements. The Group's vendors continuously change the way in which they bring their products and services to market and there is a significant amount of judgement involved in determining whether or not the Group acts as an agent or principal with regards to these arrangements. In its reassessment, the Group concluded that in those arrangements where the software service is delivered entirely by the vendor, or where the updates and cloud access are critical to the effectiveness of the solution and there is no material on-premise component to the solution, the Group will recognise revenue at the time of invoice on a net basis as the Group is acting as an agent in the transaction.
As a result, the Group has restated its 31 August 2020 ("H1 FY21") consolidated statement of comprehensive income to reflect only the fees earned, for acting as an agent in these arrangements, as revenue. This has resulted in a decrease in revenue and a corresponding decrease in cost of goods sold in H1 FY21. There was no impact on gross profit or items below gross profit in the consolidated statement of comprehensive income. In addition, there was no impact on earnings or earnings per share.
Note that despite the revenue being disclosed on a net basis, the Group has a contractual right to the gross amount of cash related to the gross revenue and therefore, for any amounts remaining unpaid at the period end, the Group continues to present these amounts as gross trade receivables in the consolidated statement of financial position. The restatement has no impact on the consolidated statement of financial position or consolidated statement of cash flows.
| Before restatement |
After restatement |
Total restatement |
||
| H1 FY21 | ||||
| Revenue (US$ million) | 2 031.2 | 1 962.9 | (68.3) | |
| Cost of sales (US$ million) | (1 707.0) | (1 638.7) | 68.3 | |
| Gross profit (US$ million) | 324.2 | 324.2 | – | |
| Gross margin (%) | 16.0 | 16.5 | 0.5 |
Divisional summary
Logicalis
Logicalis is the largest contributor to the Group in terms of profitability. The division also has the widest geographical exposure and Datatec intends to continue to develop and grow Logicalis globally, both organically and through acquisitions.
Logicalis revenue increased by 18.7% to US$822.9 million compared to US$693.1 million^ restated revenue for H1 FY21. In constant currency*** terms, Logicalis revenue increased by 15.4%. EBITDA increased by 8.0% to US$46.5 million (H1 FY21: US$43.0 million).
Global trading uncertainties are expected to persist for some time but Logicalis is confident that it is positioned to continue to respond to changing market needs as society emerges from Covid-19 disruptions. Technology is set to play an even more integral role in the "next normal" and Logicalis is ready to facilitate these fundamental changes.
Westcon International
Westcon International revenue increased by 12.3% to US$1.4 billion (H1 FY21: US$1.2 billion^ restated revenue) due to strong demand for networked cloud computing, remote access solutions for mobile working and virtual office environments, unified collaboration and enhanced network security. In constant currency*** terms, revenue improved by 7.3%. EBITDA increased by 61.1% to US$31.0 million (H1 FY21: US$19.2 million).
Westcon International remains focused on profitability by driving business improvement through revenue growth and margin expansion supported by cost controls. While several macroeconomic risks exist, the H1 FY22 results highlight Westcon International's ability to capitalise on the stability of the system and process improvements made in recent years.
Management Consulting
Analysys Mason revenue increased by 37.1% to US$43.6 million (H1 FY21: US$31.8 million). EBITDA increased by 24.6% to US$7.1 million (H1 FY21: US$5.7 million).
Analysys Mason has a strategy focused on specialisation in the TMT sector where increasingly the industries of telecommunications and information technology are converging and driving rapid digitisation across many industries often brought about by the move to cloud computing. Analysys Mason's key priority is to grow revenue while continuing to improve profitability without diluting the significant value propositions delivered by the business's exceptional talent.
Current trading and outlook
The robust performance and upward trend in all our divisions during H1 FY22 are expected to continue into the second half of the financial year as Westcon International and Logicalis look to satisfy the continuing demand for software and services in networking, security and cloud infrastructure.
Datatec's strong balance sheet provides a firm foundation to support growth and new initiatives as most economies start to rebound. The Group's well diversified business mix and global presence should result in significant opportunities despite the ongoing semiconductor shortage which is expected to continue to impact the supply chain well into 2022.
Group results
All divisions delivered solid performances with strong revenue and bottom-line growth. There were no restructuring costs incurred in H1 FY22 (H1 FY21: US$6.0 million of restructuring costs).
Emerging markets such as Brazil and South Africa were positively impacted by local currencies strengthening in H1 FY22 against the US Dollar which increased their
dollar-reported contribution to the results. The Euro and Pound have also strengthened against the US Dollar.
Datatec Financial Services, previously reported in the "Corporate and Management Consulting" segment has been moved to Westcon International during FY22 in order to leverage the capabilities and scale of both businesses.
Revenue
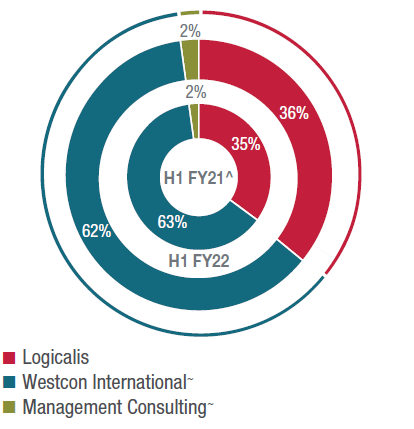
Group revenue was US$2.26 billion in H1 FY22, up by 15.0% on the US$1.96 billion^ restated revenue recorded in the financial period ended 31 August 2020. In constant currency*** terms, Group revenue increased by 10.7%.
Contribution to Group revenue
| ^ | H1 FY21 restated. |
| ~ | Datatec Financial Services has been included in the Westcon International segment in H1 FY22 and in the Corporate segment in H1 FY21. |
The Group's backlog has risen across all sectors as digitisation-driven pent-up demand continues to grow for new technologies to enable increased cloud usage.
The Group's gross margin in H1 FY22 was 16.6% compared to 16.5% (restated) in H1 FY21. Gross profit was US$374.4 million (H1 FY21: US$324.2 million).
Contribution to Group gross profit

| ~ | Datatec Financial Services has been included in the Westcon International segment in H1 FY22 and in the Corporate segment in H1 FY21. |
Overall operating costs were US$299.4 million (H1 FY21: US$263.5 million). Restructuring costs of US$6.0 million were included in the prior period relating to fundamental reorganisations and Covid-19-related restructuring. There were no such restructuring costs in H1 FY22.
EBITDA was US$75.0 million (H1 FY21: US$60.7 million and H1 FY21 Adjusted** EBITDA: US$66.7 million) and included US$5.1 million of foreign exchange losses (H1 FY21: US$2.2 million). EBITDA margin was 3.3% (H1 FY21: 3.1% restated).
Foreign exchange losses consisted of unrealised foreign exchange losses of US$2.2 million (H1 FY21 unrealised foreign exchange gains: US$4.1 million) and realised foreign exchange losses of US$2.9 million (H1 FY21: US$6.3 million). Unrealised foreign exchange differences are excluded from underlying* earnings per share.
Depreciation and amortisation increased to US$35.9 million (H1 FY21: US$32.7 million) and operating profit was US$39.1 million (H1 FY21: US$28.0 million).
The net interest charge increased slightly to US$14.2 million (H1 FY21: US$13.4 million) and profit before tax was US$25.4 million (H1 FY21: US$15.4 million).
A tax charge of US$8.6 million has arisen on profits of US$25.4 million. The effective tax rate of 34.0% has benefited from the revaluation of deferred tax assets arising from the increase in the UK corporation tax rate enacted earlier in the year. The effective tax rate continues to reduce as profits grow and the profit mix continues to improve. As at 31 August 2021, there are estimated tax loss carry forwards of US$240.5 million with an estimated future tax benefit of US$61.1 million, of which only US$28.2 million has been recognised as a deferred tax asset.
Underlying* earnings per share were 8.3 US cents (H1 FY21: 3.9 US cents). Headline earnings per share were 6.3 US cents (H1 FY21: 1.6 US cents). Earnings per share were 6.3 US cents (H1 FY21: 1.6 US cents).
Cash and net debt
The Group utilised US$4.6 million of cash in operations during H1 FY22 (H1 FY21: cash generated of US$134.2 million) and ended the period with a net debt of US$152.5 million (FY21: US$60.9 million; H1 FY21: US$73.2 million). Excluding lease liabilities, net debt would have been US$49.8 million (H1 FY21: net cash of US$75.6 million).
The operating cash outflows were mainly as a result of an increase in inventory in Westcon International, as well as increased receivables on the back of the very strong revenue growth.
| US$'000 | Unaudited Six months to 31 August 2021 |
Unaudited Six months to 31 August 2020 |
Audited Year ended 28 February 2021 |
|
| Cash resources | 492.7 | 406.7 | 488.6 | |
|---|---|---|---|---|
| Bank overdrafts‡# | (143.3) | (271.1) | (131.4) | |
| Short-term interest-bearing liabilities and short-term leases | (393.4) | (71.8) | (297.9) | |
| Long-term interest-bearing liabilities and long-term leases | (108.5) | (137.0) | (120.2) | |
| Net debt | (152.5) | (73.2) | (60.9) |
| ‡ | The Group restated its statement of cash flows for H1 FY21 to exclude certain bank overdrafts from cash and cash equivalents. Bank overdrafts that are repayable on demand under certain circumstances, but not unconditionally repayable on demand have now been excluded from cash and cash equivalents and cash flows associated with these bank overdrafts are now shown as cash flows from financing activities. The restatement relates to banking arrangements that form an integral part of the Group's cash management. This restatement did not impact the statement of financial position or the net cash/debt of the Group or its subsidiaries. |
| # | During the second half of FY21, Westcon International replaced its previous European invoice financing facility with a new invoice assignment facility. The new invoice assignment facility is accounted for as short-term debt compared to the previous facility which was accounted for as part of bank overdrafts. |
Liquidity and borrowing facilities
The Group continues to closely monitor the outlook for liquidity in its divisions to ensure that sufficient cash will continue to be generated to settle liabilities as they fall due.
Logicalis is supported by a corporate facility of US$155.0 million, covering all operations outside of Latin America, comprising a rolling credit facility to fund working capital requirements and an acquisition facility. The Latin America region is supported separately via a number of uncommitted overdraft facilities and short-term lending arrangements.
Westcon International has an invoice assignment facility of EUR275.0 million for its European subsidiaries and a securitisation facility of US$80.0 million for its Asia-Pacific subsidiaries. In addition, Westcon International utilises accounts receivable facilities in the Middle East (US$15.0 million) and Indonesia (US$11.0 million) as well as overdraft facilities in Europe (GBP3.6 million) and Africa (US$1.0 million), a securitisation facility in South Africa (ZAR50.0 million) and a line of credit in Singapore (US$1.2 million) to finance the business.
Analysys Mason continues to have access to an overdraft supporting its working capital requirements.
The Group continues to monitor the funding needs of its individual operations and works closely with various financial institutions to ensure adequate liquidity.
The Group has performed covenant projections for the next 12 months to confirm that banking covenants are expected to be met.
Acquisitions
On 1 March 2021, Logicalis Group's 65% held subsidiary PromonLogicalis Latin America Limited, exercised its option to acquire an additional interest of 20.1% of the issued share capital in Kumulus for US$1.2 million. Kumulus will continue to be equity-accounted for in the Group's results because the Group does not have management control.
On 31 March 2021, Logicalis acquired 70% of the issued share capital in Áudea, a Spanish company which specialises in cyber security and data protection, governance and compliance, for a consideration of US$2.1 million cash. Áudea's cyber security capabilities are complementary to Logicalis Spain's security portfolio, creating a much broader professional and managed service offering.
On 1 June 2021, Logicalis acquired Siticom, a German company that is a leading services and solutions provider in the software-defined networking and 5G market, through a new company, Logicalis Siticom GmbH. The transaction involved the acquisition of 100% of the issued share capital for a consideration of US$12.7 million followed by the immediate disposal of 29.6% of the issued share capital to two of the previous owners/managers for a consideration of US$5.4 million. There are two options for Logicalis to repurchase this non-controlling interest for an agreed amount of up to US$10.5 million over the next two years, whereafter Logicalis will own 100% of Siticom. Of this agreed amount, US$9.3 million is required to settle these options and has been placed in an escrow account that is not reflected as part of cash and cash equivalents, but included in other receivables.
A potential maximum EUR1.0 million (approximately US$1.2 million) earn-out liability, subject to certain performance conditions, is included in the purchase price and payable in the financial year ending 29 February 2024. Due to these fixed priced options, Logicalis consolidated 100% of the results of Siticom for the period it was owned in H1 FY22, and will continue to do so in the future. The total purchase price of the Siticom acquisition (including the options and earn-out liability) is up to a maximum of EUR15.0 million (approximately US$17.9 million), of which US$10.5 million is accounted for as a liability at the acquisition date and included in acquisition-related liabilities.
For further information see acquisitions made during the period.
Divisional reviews
Logicalis
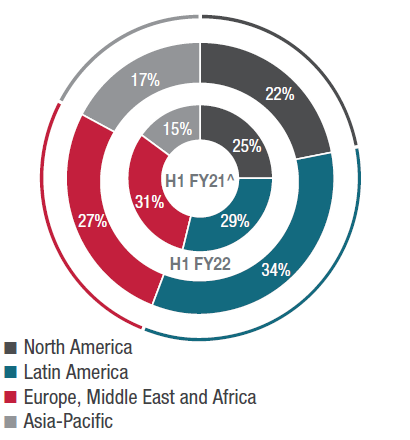
Logicalis revenue increased by 18.7% to US$822.9 million compared to US$693.1 million^ restated revenue for H1 FY21. In constant currency*** terms Logicalis revenue increased by 15.4%. Revenue increased across all regions in absolute terms except for Europe, which was marginally lower, taking into account contributions from the Áudea and Siticom acquisitions completed during H1 FY22. The lower profile in the Europe region is impacted by a significant customer transaction delivered in Germany during H1 FY21.
Revenue contribution by geography is shown below:
Logicalis revenue %
contribution by geography
^ H1 FY21 restated.
Logicalis had a strong order intake during H1 FY21. Shipment delays as a result of global supply chain issues resulted in a significant increase in backlog, impacting Latin America, Europe, Middle East and Africa the most.
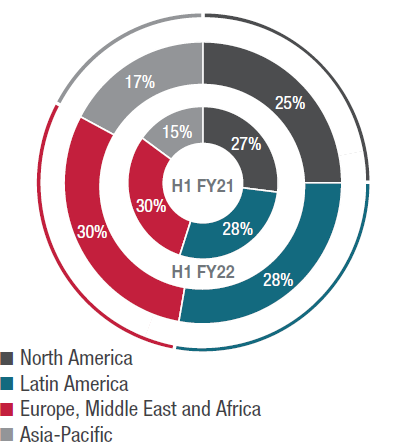
Logicalis' gross margin was 24.2% (H1 FY21: 25.5% restated). Underlying gross margin percentage remained solid with the headline decrease being caused by the higher mix of product delivered in H1 FY22. Gross profit was up 12.7% to US$199.3 million (H1 FY21: US$176.9 million).
Logicalis' gross profit contribution by geography is shown below:
Logicalis gross profit %
contribution by geography
Operating costs increased to US$152.8 million (H1 FY21: US$133.9 million). The H1 FY22 growth in cost reflects a return to increased selling activity and incremental spend in areas such as marketing and training programmes following restrictive Covid-19 measures implemented during FY21. EBITDA was US$46.5 million (H1 FY21: US$43.0 million), with a corresponding EBITDA margin of 5.7% (H1 FY21: 6.2% restated). Operating profit was US$24.7 million (H1 FY21: US$23.1 million).
The net interest charge increased by US$0.9 million, reflecting the impact of base interest rate increases in Brazil.
The increase in net debt compared to H1 FY21 was driven primarily by increased volume of business, increasing working capital requirements and acquisitions made during the period.
| US$'000 | Unaudited Six months to 31 August 2021 |
Unaudited Six months to 31 August 2020 |
Audited Year ended 28 February 2021 |
|
| Cash resources | 150.3 | 198.4 | 154.4 | |
|---|---|---|---|---|
| Bank overdrafts | (135.2) | (144.3) | (126.5) | |
| Short-term interest-bearing liabilities and short-term leases | (88.4) | (60.8) | (69.4) | |
| Long-term interest-bearing liabilities and long-term leases | (73.8) | (83.0) | (81.9) | |
| Net debt | (147.1) | (89.7) | (123.4 ) |
Logicalis has a contingent liability in respect of a possible tax liability at its PromonLogicalis Latin America Limited ("PromonLogicalis") subsidiary in Brazil. In April 2011, a Brazilian state tax authority claimed that PromonLogicalis should have paid a higher rate of state tax on its equipment sales up to October 2010 than actually paid. PromonLogicalis management, supported by a legal opinion, strongly disagrees with the state tax authority's assessment and has formally appealed against it.
In addition, Logicalis has a contingent tax liability at its PT Packet Systems subsidiary in Indonesia. The tax authorities have raised withholding tax assessments, including penalties and surcharges in relation to purchases of vendor software and warranties which have been resold to customers. Assessments have been issued for calendar years 2015 and 2016 and the two months ended February 2018. Objections have been filed by the company in respect of these and year 2015 has progressed to the tax court which gave an adverse verdict. The company is appealing to the Supreme Court. Management, supported by a legal opinion, expects this decision to be reversed on appeal and therefore no provision has been made at 31 August 2021.
Logicalis continues to develop its capabilities within cloud, Internet of Things ("IoT"), software, security, data management and intelligent networks in support of its strategy to provide full lifecycle services around IT infrastructure solutions to its customers.
The future will likely involve hybrid workplaces of part-time office and remote workers. Preparing and planning for this environment will be essential in providing a better digital experience for customers, partners and employees.
Creating greater operational resilience for Logicalis and its customers will be critical. Organisations may find themselves reassessing and reprioritising their business operations and technological needs, deeming the systems, processes and data insight they had in place pre-pandemic as no longer sufficient or relevant. Upskilling and training employees will also be key in addressing any digital skills gaps and building a more resilient workforce.
Logicalis remains confident about the long-term prospects for the industry and its positioning within it. Over the short term, emerging markets currencies and interest rates are expected to remain volatile. Logicalis continues to monitor the impact of the global semiconductor shortage on its business and customers.
Westcon International
Westcon International revenue increased by 12.3% to US$1.4 billion (H1 FY21: US$1.2 billion^ restated revenue) due to strong demand for networked cloud computing, remote access solutions for mobile working and virtual office environments, unified collaboration and enhanced network security. In constant currency*** terms, revenue improved by 7.3%.
Westcon International's backlog also increased significantly as a result of the semiconductor shortage and supply chain constraints.
Westcon International's gross margins increased to 11.1% (H1 FY21: 10.8% restated) with higher margins in the Middle East and Africa ("MEA") and Asia-Pacific (Europe margin flat). Westcon International's gross profit increased by 15.8% to US$155.0 million (H1 FY21: US$133.9 million) with higher results across all regions.
Westcon International revenue %
contribution by geography
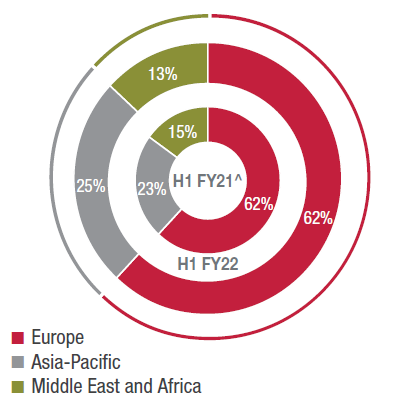
^ H1 FY21 restated.
Westcon International gross profit %
contribution by geography

Operating costs increased by 8.1% to US$124.0 million (H1 FY21: US$114.7 million) with higher costs across all regions, largely due to a weakened US Dollar and an increase in share-based payment charges. Central costs of US$13.5 million were incurred in H1 FY22 (H1 FY21: US$13.0 million).
EBITDA increased by 61.1% to US$31.0 million (H1 FY21: US$19.2 million) with favourable results in Europe (62% growth), MEA and Asia-Pacific. EBITDA margin increased to 2.2% (H1 FY21: 1.6% restated).
Net working capital days increased to 20 days (FY21: 18 days; H1 FY21: 17 days) as a reduction of inventory turns was partially offset by continued improvement in days sales outstanding ("DSO"). Net debt was US$141.4 million (FY21: US$19.0 million; H1 FY21: US$33.5 million) with the increase attributable to a combination of Datatec debt repayments and increased working capital requirements (primarily higher inventory due to increased customer demand).
| US$'000 | Unaudited Six months to 31 August 2021 |
Unaudited Six months to 31 August 2020 |
Audited Year ended 28 February 2021 |
|
| Cash resources | 198.5 | 146.2 | 243.1 | |
|---|---|---|---|---|
| Bank overdrafts | (8.1) | (124.0) | (4.9) | |
| Short-term interest-bearing liabilities and short-term leases | (302.9) | (9.5) | (225.4) | |
| Long-term interest-bearing liabilities and long-term leases | (28.9) | (46.2) | (31.8) | |
| Net debt | (141.4) | (33.5) | (19.0 ) |
Datatec Financial Services provides financing/leasing solutions for ICT customers. The business has been moved to Westcon International during FY22 in order to leverage the capabilities and scale of both businesses. The business recorded revenue of US$0.1 million in H1 FY22 (H1 FY21: US$0.3 million) and an EBITDA loss of US$0.7 million (H1 FY21: US$0.4 million loss). The H1 FY22 results are included in the Westcon International segment with the H1 FY21 results included in the "Corporate and Management Consulting" segment.
Westcon International has a contingent liability in respect of a possible withholding tax obligation at its subsidiary in the Kingdom of Saudi Arabia, Westcon Saudi Company LLC ("Westcon KSA"). This relates to payments Westcon KSA has made in relation to the purchase of vendor software and maintenance services which have been resold to customers during the six years ended 28 February 2021. Westcon KSA strongly disagrees with the tax authority's assessments issued on 22 June 2021 and is taking the necessary steps to contest these. In addition, a potential contingent asset also arises due to the fact that any withholding tax arising would potentially be recoverable from Westcon KSA's customers. The ongoing discussions with the KSA tax authorities are likely to continue well into the foreseeable future and given the discussions are still in very early stages, it is not practicable to estimate its financial effect.
Current conditions are driving demand for all technologies in the Westcon International portfolio. The multi-year investments in advanced systems and business automation have enabled the business to record double-digit revenue growth despite the product supply constraints.
The global semiconductor shortage continues to impact all technology participants across multiple verticals. Westcon International continues to monitor and mitigate the impact on availability and costs where possible.
Corporate and Management Consulting
The Management Consulting unit delivered an excellent performance in H1 FY22. Revenue increased by 37.1% to US$43.6 million (H1 FY21: US$31.8 million). Gross profit increased by 53.4% to US$20.1 million from US$13.1 million in H1 FY21. EBITDA increased by 24.6% to US$7.1 million (H1 FY21: US$5.7 million) and EBITDA margin decreased to 16.3% compared to 17.9% in H1 FY21.
Analysys Mason continues to focus on bringing together commercial and technical understanding to deliver bespoke consultancy on strategy, transaction support, transformation, regulation and policy, further strengthened by globally respected research. Although markets remain challenging and unpredictable in the short to medium term, management believes that the overall outlook is positive and Analysys Mason continues to enjoy a good level of repeat business with its existing customers while attracting new clients.
Datatec Financial Services, previously reported in the Corporate and Management Consulting segment has been moved to Westcon International during FY22 in order to leverage the capabilities and scale of both businesses.
Corporate includes the net operating costs of the Datatec head office entities which were US$9.1 million (H1 FY21: US$7.4 million). The increase is mainly as a result of increased share-based payment charges. Corporate costs include the remuneration of the Board and head office staff, consulting and audit fees. In H1 FY22, foreign exchange losses were US$0.5 million (H1 FY21: foreign exchange gains of US$0.6 million).
As at 31 August 2021, Datatec head office entities held cash of US$128.5 million of which US$6.9 million (including ZAR10.8 million held in ZAR) is held in South Africa and subject to the South African Reserve Bank regulations. These cash balances increased by US$54.3 million from 28 February 2021 mainly as a result of settlement of intercompany loans from subsidiaries net of dividends paid to shareholders of Datatec.
Subsequent events
There were no material events that occurred subsequent to the reporting date that require disclosure or adjustment to these results.
Board changes
The following changes to the functions of directors were announced during H1 FY22:
- Johnson Njeke, independent non-executive director of the Company, was appointed to the Social and Ethics Committee with effect from 1 March 2021.
- Maya Makanjee, independent non-executive director of the Company, will become Chair of the Board in succession to Stephen Davidson on 1 March 2022.
Special cash dividend with scrip distribution alternative
Introduction
In accordance with the intention of the Board detailed above to return US$70 million to ordinary shareholders (the "Shareholders") from intercompany loans repaid by Westcon International to Datatec during H1 FY22, notice is hereby given that the Board has declared a special distribution by way of a special cash dividend of 512 ZAR cents per Datatec ordinary share ("Special Cash Dividend") payable to the Shareholders, which will be in proportion to your ordinary shareholding in Datatec at the close of business on the Record Date, being Friday, 26 November 2021.
Shareholders will be entitled, in respect of all or part of their shareholding, to elect to receive new, fully paid ordinary Datatec shares in proportion to their ordinary shareholding on the Record Date as an alternative to the Special Cash Dividend (the "Scrip Distribution"). The Special Cash Dividend has been declared and paid out of Datatec's distributable retained profits. A dividend withholding tax of 20% will be applicable in respect of the Special Cash Dividend to all shareholders not exempt therefrom after deduction of which, the net Special Cash Dividend is 409.6 ZAR cents per share.
The new ordinary shares will, pursuant to the Scrip Distribution, not be subject to a dividend withholding tax, and the issue price of the Scrip Distribution (which will equal the volume weighted average price ("VWAP") of Datatec's ordinary shares traded on the JSE for the 30-day trading day period ending on Monday, 15 November 2021 will be settled by way of a capitalisation of Datatec's distributable retained profits.
The Company's total number of issued ordinary shares as at 28 October 2021 is 203 178 104. Datatec's income tax reference number is 9999/493/71/2.
Terms of the Special Cash Dividend and Scrip Distribution
The Shareholders will be entitled to receive the Special Cash Dividend of 512 ZAR cents per ordinary Datatec Share in respect of their shareholding as at the close of trading on the JSE at the close of business on the Record Date, being Friday, 26 November 2021, in proportion to their ordinary shareholding in Datatec and to the extent that such Shareholders have not elected to receive the Scrip Distribution alternative in respect of all or a part of their shareholding.
Shareholders will, however, be entitled to elect to receive a Scrip Distribution of new, fully paid Datatec ordinary shares in respect of their shareholding in Datatec as at the Record Date, in respect of all or part of their ordinary shareholding, instead of the Special Cash Dividend.
The number of Scrip Distribution shares to which each of the Shareholders will become entitled pursuant to the Scrip Distribution (subject to their election thereto) will be determined by reference to such Shareholder's ordinary shareholding in Datatec (at the close of business on the Record Date, being Friday, 26 November 2021) in relation to the ratio that 512 ZAR cents bears to the VWAP of a Datatec ordinary share traded on the JSE during the 30-day trading period ending on Monday, 15 November 2021, provided that, where the application of this ratio gives rise to a fraction of an ordinary share, the rounding principles will be applied. Where a Shareholder's entitlement to new Datatec ordinary shares calculated in accordance with the above formula gives rise to a fraction of a new ordinary share, such fraction of a new ordinary share will be rounded down to the nearest whole number, resulting in allocations of whole ordinary shares and a cash payment for the fraction. The applicable cash payment will be determined with reference to the VWAP of an ordinary Datatec share traded on the JSE on Wednesday, 24 November 2021, (being the day on which Datatec ordinary shares begin trading 'ex' the entitlement to receive the Special Cash Dividend or the Scrip Distribution alternative), discounted by 10%.
Details of the ratio will be announced on the Stock Exchange News Service ("SENS") of the JSE in accordance with the timetable below.
Circular and salient dates
A circular providing Shareholders with full information on the Special Cash Dividend or Scrip Distribution alternative, including a Form of Election to elect to receive the Scrip Distribution alternative will be distributed to Shareholders on or about Wednesday, 3 November 2021. The salient dates of events thereafter are as follows:
| EVENT | 2021 | |
| Interim financial results of Datatec for the six-month period ended 31 August 2021 and declaration of Special Cash Dividend with Scrip Distribution alternative announced on SENS on | Thursday, 28 October |
|
| Interim financial results of Datatec for the six-month period ended 31 August 2021 and declaration of Special Cash Dividend with Scrip Distribution alternative published in the South African press on | Friday, 29 October |
|
| Distribution of Circular announced on SENS on | Wednesday, 3 November |
|
| Circular and Form of Election distributed on | Wednesday, 3 November |
|
| Distribution of Circular announcement published in the South African press on | Thursday, 4 November |
|
| Announcement released on SENS in respect of the ratio applicable to the Scrip Distribution alternative, based on the 30-day VWAP ending on Monday, 15 November 2021, by 11:00 on | Tuesday, 16 November |
|
| Announcement published in the South African press of the ratio applicable to the Scrip Distribution alternative, based on the 30-day VWAP ending on Monday, 15 November 2021 on | Wednesday, 17 November |
|
| Last day to trade in order to be eligible for the Special Cash Dividend and the Scrip Distribution alternative | Tuesday, 23 November |
|
| Shares trade "ex" the Special Cash Dividend and the Scrip Distribution alternative on | Wednesday, 24 November |
|
| Listing and trading of maximum possible number of Datatec ordinary shares on the JSE in terms of the Scrip Distribution alternative from the commencement of business on | Wednesday, 24 November |
|
| Announcement released on SENS in respect of the cash payment applicable to fractional entitlements, based on the VWAP of a Datatec ordinary share traded on the JSE on Wednesday, 24 November 2021, discounted by 10%, by 11:00 on | Thursday, 25 November |
|
| Last day to elect to receive the Scrip Distribution alternative instead of the Special Cash Dividend, Forms of Election to reach the transfer secretaries, Computershare Investor Services Proprietary Limited, by 12:00 on | Friday, 26 November |
|
| Record Date in respect of the Special Cash Dividend and the Scrip Distribution alternative | Friday, 26 November |
|
| Special Cash Dividend payments made, and CSDP/broker accounts credited/updated with Scrip Distribution shares on | Monday, 29 November |
|
| Announcement relating to the results of the Special Cash Dividend and the Scrip Distribution alternative released on SENS on | Monday, 29 November |
|
| Announcement relating to the results of the Special Cash Dividend and the Scrip Distribution alternative published in the South African press on | Tuesday, 30 November |
|
| JSE listing of Shares in respect of the Scrip Distribution alternative adjusted to reflect the actual number of Datatec ordinary shares issued in terms of the Scrip Distribution alternative at the commencement of business on or about | Tuesday, 30 November |
All times provided are South African local times. The above dates and times are subject to change. Any material change will be announced on SENS.
Share certificates may not be dematerialised or rematerialised between Wednesday, 24 November 2021 and Friday, 26 November 2021, both days inclusive. If Datatec maintains a certificated register, then the register will be closed from Wednesday, 24 November 2021 to Friday, 26 November 2021, both days inclusive.
Payment of the Special Cash Dividend and the Scrip Distribution alternative has been approved by the Financial Surveillance Department of the South African Reserve Bank.
Disclaimer
This announcement may contain statements regarding the future financial performance of the Group which may be considered to be forward-looking statements. By their nature, forward-looking statements involve risk and uncertainty, and although the Group has taken reasonable care to ensure the accuracy of the information presented, no assurance can be given that such expectations will prove to have been correct.
The Group has attempted to identify important factors that could cause actual actions, events or results to differ materially from those described in forward-looking statements and there may be other factors that cause actions, events or results not to be as anticipated, estimated or intended. It is important to note, that:
- unless otherwise indicated, forward-looking statements indicate the Group's expectations and have not been reviewed or reported on by the Group's external auditors;
- actual results may differ materially from the Group's expectations if known and unknown risks or uncertainties affect its business, or if estimates or assumptions prove inaccurate;
- the Group cannot guarantee that any forward-looking statement will materialise and, accordingly, readers are cautioned not to place undue reliance on these forward-looking statements; and
- the Group disclaims any intention and assumes no obligation to update or revise any forward-looking statement even if new information becomes available, as a result of future events or for any other reason, other than as required by the JSE Limited Listings Requirements.
On behalf of the Board
SJ Davidson
Chair
JP Montanana
Chief Executive Officer
IP Dittrich
Chief Financial Officer
28 October 2021
Directors
SJ Davidson# (Chair), JP Montanana# (CEO), IP Dittrich (CFO), M Makanjee, JF McCartneyo, CRK Medlock#, MJN Njeke, E Singh-Bushello
o American #British
| * | Excluding impairments of goodwill and intangible assets, profit or loss on sale of investments and assets, amortisation of acquired intangible assets, unrealised foreign exchange movements, acquisition-related adjustments, fair value movements on acquisition-related financial instruments, restructuring costs relating to fundamental reorganisations and the taxation effect on all of the aforementioned. |
| ** | Adjusted EBITDA excludes restructuring costs. |
| *** | The pro forma constant currency and adjusted EBITDA information, which is the responsibility of the Datatec directors, presents the Group's revenue for the current reporting period had it been translated at the average foreign currency exchange rates of the prior reporting period as well as EBITDA had restructuring costs not been incurred. This information is for illustrative purposes only and because of its nature, may not fairly present the Group's results. To determine the revenue in constant currency terms, the current financial reporting period's monthly revenues in local currency have been converted to US dollars at the average monthly exchange rates prevailing over the same period in the prior period. Refer to Pro forma supplementary information for more information on the calculation of constant currency information. |

